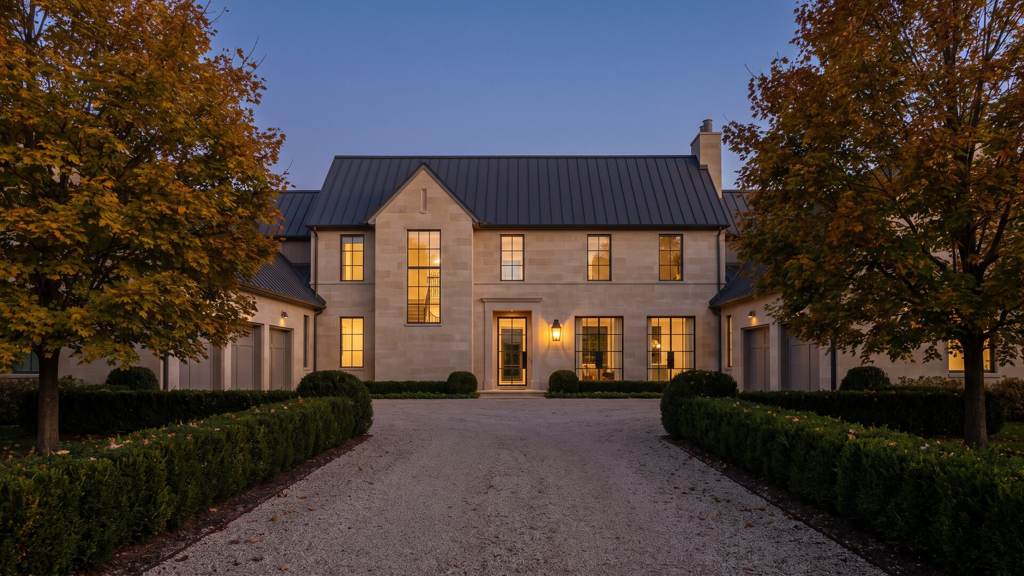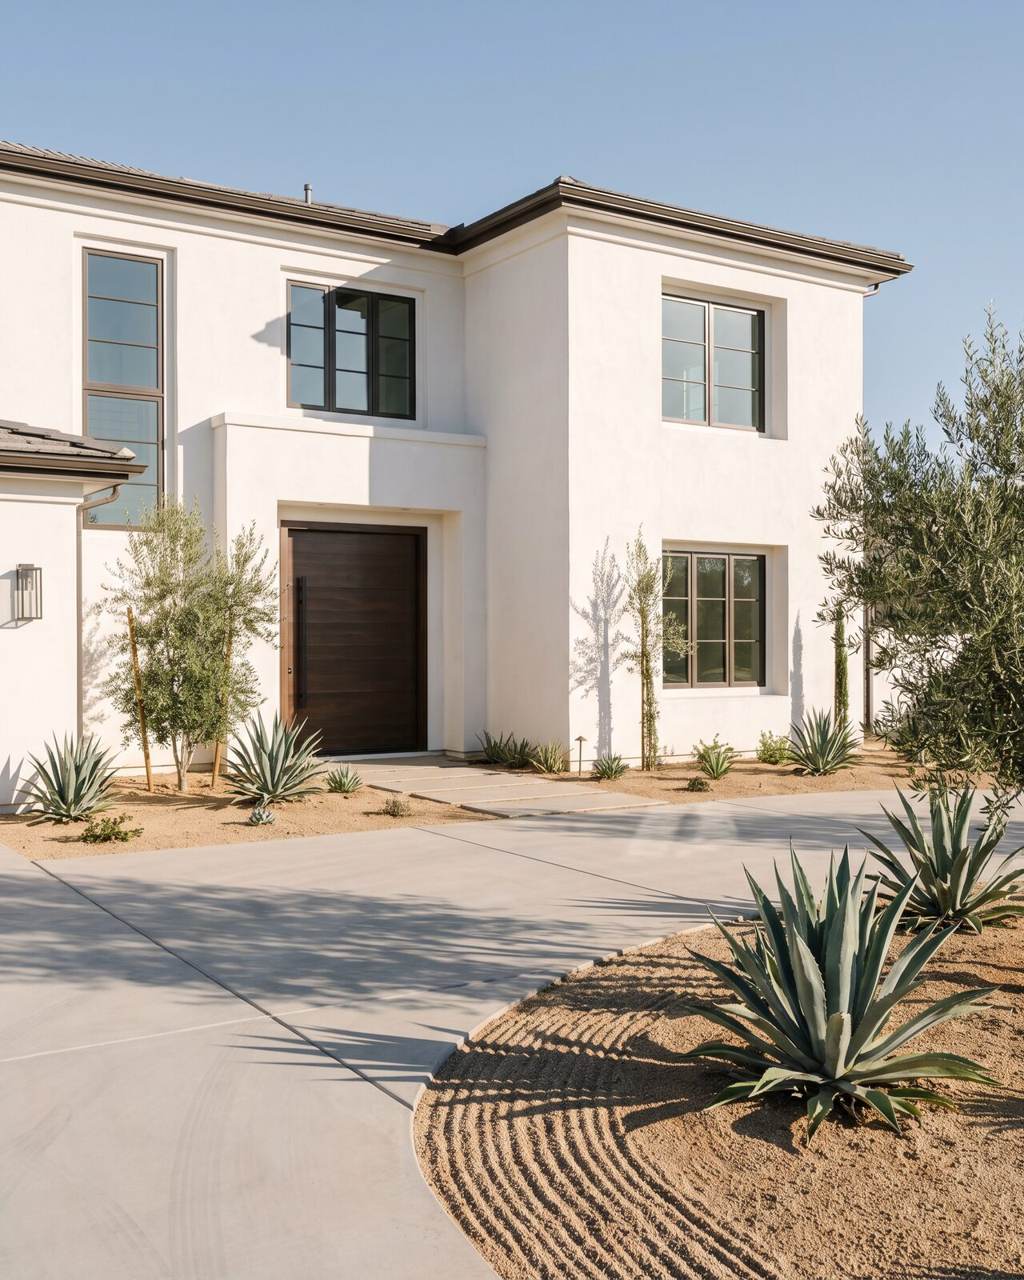

Every fall, luxury inventory does something the mid-market often cannot: it reappears with intention. Labor Day closes the summer show-circuit; sellers who waited for cleaner photography, school calendars, or a quieter negotiation window return to the market; and buyers who postponed decisions through August resume touring with sharper criteria. The question that matters for homes at $700,000 and above is not simply whether “the market” is hot or cool. It is which buyer clears the listing — and on what terms.
Two cultures now share the same open houses. On one side sit cash purchasers and rate-insulated households who treat financing as optional theater: portfolio liquidity, equity from a prior sale, or the ability to close without waiting on a rate lock. On the other sit capable, motivated shoppers whose offers still depend on underwriting, appraisal paths, and monthly payment math. Both can afford beautiful homes. Only one group reliably wins when desirable inventory is scarce, priced to today’s comps, and contested by peers who value certainty as much as square footage.
Luxury Hôm’s Market brief for fall is therefore practical, not prophetic: understand how cash and rate insulation shape who gets the key — then price, prepare, and compete accordingly.
The intentional luxury market, not the frantic one
Industry pulse readings for 2026 describe a luxury buyer who is still present, still solvent, and less impulsive than in the peak years. Christie’s International Real Estate’s 2026 Market Pulse put its composite Property Sentiment Index at +14.4 — still expansionary, yet cooler than the +15.6 reading in the prior outlook cycle. The editorial takeaway is not collapse; it is deliberation. Demand remains constructive, but buyers are more intentional: fit, long-term confidence, and lifestyle alignment outweigh pure urgency.
That intentionality favors the cash and rate-insulated cohort. A shopper who can write a clean offer without rate contingency drama is freer to focus on architecture, light, outdoor rooms, and whether the house will still feel right a decade from now. A financing-dependent shopper may love the same house and still lose on timeline, contingency stack, or the seller’s preference for a sure close. In an intentional market, certainty is a luxury amenity.
Compass’s Housing Market Outlook framing for 2026 — a more balanced national backdrop, with inventory projected higher while luxury at the million-dollar-plus tier continues to outperform thinner entry-level segments — reinforces the same split. Upper-tier homes are not immune to seasonality or local oversupply, but they often clear through a buyer pool that is structurally less rate-sensitive than the broader market. Realtor.com’s luxury research has long noted that cash share rises with price; in one cited Miami-tier analysis, cash reached 84.7% of transactions in the $5M–$10M band. Exact percentages vary by metro and month. The pattern does not: the higher you climb, the more the winning bid looks like liquidity, not leverage.
Who actually clears $700k+ inventory this fall
Cash and rate-insulated buyers win when the home is correctly priced, photographically credible, and in a location with competing interest. Their advantages are procedural as much as financial: shorter contingency chains, fewer financing surprises, and the ability to move on a seller’s preferred calendar. In fall, when new listings arrive in clusters after the holiday weekend, that speed matters. A well-presented house can collect multiple serious showings in the first ten days; the offer that feels bankable often outranks the offer that is merely higher on paper.
Rate-sensitive and financing-dependent shoppers still clear inventory — especially homes that sit past the first marketing wave, carry a sticky ask, or need a buyer willing to underwrite renovation. Their path is narrower. Payment sensitivity can push them toward slightly smaller footprints, secondary views, or metros where the luxury threshold has eased.
Realtor.com’s July 2026 luxury report noted that the national luxury entry point (90th percentile) sat near $1,250,750, down 2.7% year over year — the 29th consecutive month of annual declines in that threshold measure — even as top-decile homes sold in a median 68 days, three days faster than a year earlier. In plain language: the gate to “luxury” by national definition has softened in places, yet desirable homes still move when they are right. Financing buyers who act like cash buyers — strong pre-approval, tight contingencies, decisive tours — remain competitive. Those who wait for a perfect rate print often watch the house go to someone who did not need one.
The fall implication is asymmetric. Cash does not automatically overpay; it often underwrites certainty. Rate-sensitive buyers who want the same certainty must bring preparation that substitutes for liquidity: documentation ready, inspectors booked, and a willingness to compete on timing and cleanliness of terms rather than on hope that rates alone will reopen the field.
What sellers should do with a two-speed buyer pool
Sellers who price to 2022 peak nostalgia gift time to the wrong audience. The buyers who can close tomorrow are comparing today’s comps, today’s days-on-market, and today’s condition — not last cycle’s cocktail-party number. Pricing into the cash and rate-insulated lane means landing where a liquid buyer feels slightly early, not late: tight enough to generate traffic in week one, honest enough that appraisal or portfolio review does not become a week-four renegotiation.
Presentation still separates cleared inventory from languishing inventory. Fall light is editorial; outdoor rooms still show; systems and wellness cues — the same longevity and lifestyle priorities Sotheby’s outlook language has elevated, with agents citing lifestyle as increasingly important (in Mid-Year survey work, lifestyle registered ahead of several macroeconomic worries) — help a listing feel finished rather than merely staged. Cash buyers are not sentimental about dated mechanicals. They are efficient about discounts. A house that photographs as complete earns the certainty premium; a house that photographs as a project invites financing buyers to negotiate as if they are doing the seller a favor.
Sotheby’s January 2026 Luxury Outlook also floated a familiar luxury truth in new packaging: first-mover advantage for both sides. Listing while comparable inventory is still digestible can mean cleaner competition among liquid buyers. Waiting for “better rates to bring everyone back” can mean sharing the stage with more listings and more rate-sensitive hesitation — a slower auction with a different cast.
Contingency strategy belongs in the listing conversation. Some sellers will still prefer a higher financed offer with strong earnest money and a proven local lender. Many will prefer a slightly leaner cash path. Know which buyer your price and marketing are courting before you reject the first clean offer waiting for a mythical better one.
What competing buyers should do — on either side of the rate line
If you are cash or rate-insulated, fall is a season for decisive taste, not for performing patience as a personality trait. Intentional markets reward the buyer who has already decided what lifestyle the house must support — privacy, multigenerational flexibility, recovery space, school access, a garden that works after dark — and who can say yes when that brief appears. Tour early in the listing cycle. Write terms that respect the seller’s calendar. Do not confuse liquidity with license to lowball a correctly priced home; the next cash buyer is often one showing behind you.
If you are financing-dependent, compete on professionalism. Arrive with a pre-approval that matches the price band, not a vague comfort letter. Shorten contingencies where risk is genuinely understood. Consider bridges, portfolio loans, or larger down payments that reduce payment shock and seller anxiety — tools that move you closer to the cash experience without requiring a wire for the full price. Be geographically and architecturally flexible where your rate sensitivity is highest; reserve rigidity for the few attributes you will not compromise. And watch local inventory carefully: in metros where supply has loosened, patience can be a strategy; in tight luxury pockets, patience is how you become the underbidder in someone else’s closing statement.
Both cohorts should ignore national averages as a substitute for neighborhood truth. Florida’s luxury outperformance — Miami and Tampa posting double-digit year-over-year luxury price gains in Redfin’s mid-year 2026 read, with national luxury advancing more modestly — is a reminder that “cash wins” plays out differently in a bidding climate than in a soft suburban pocket with months of supply. The buyer culture matters; the map matters more.
The fall scorecard
Who wins luxury inventory this fall? Usually the buyer who can close like cash — whether or not every dollar arrives as cash. Rate insulation, clean terms, and intentional criteria clear well-priced homes. Financing-dependent shoppers win when they borrow that playbook, or when they target inventory that liquid buyers have already passed over for reasons of condition, price, or fit.
Sellers who understand the split stop asking whether “buyers are out there” in the abstract. They ask whether their buyer is the certainty buyer or the payment buyer — then price, stage, and negotiate for that person. Buyers who understand the split stop waiting for a single national rate story to anoint the season. They decide what they can underwrite today, and they tour like it matters.
Luxury Lives Here is not a slogan about immunity to the economy. It is a reminder that at the upper end, the decisive variable is often conviction backed by liquidity — and that fall, when inventory returns with purpose, is when that conviction shows up in signed contracts.
Sources informing this edit include Christie’s International Real Estate 2026 Market Pulse; Compass Housing Market Outlook 2026; Realtor.com Luxury Housing Outlook / July 2026 luxury reporting; Sotheby’s International Realty 2026 Luxury Outlook and Mid-Year Luxury Outlook; and Redfin’s Florida luxury market release (July 2026 data). Figures are attributed to those sources and are not restated as Luxury Hôm originals.