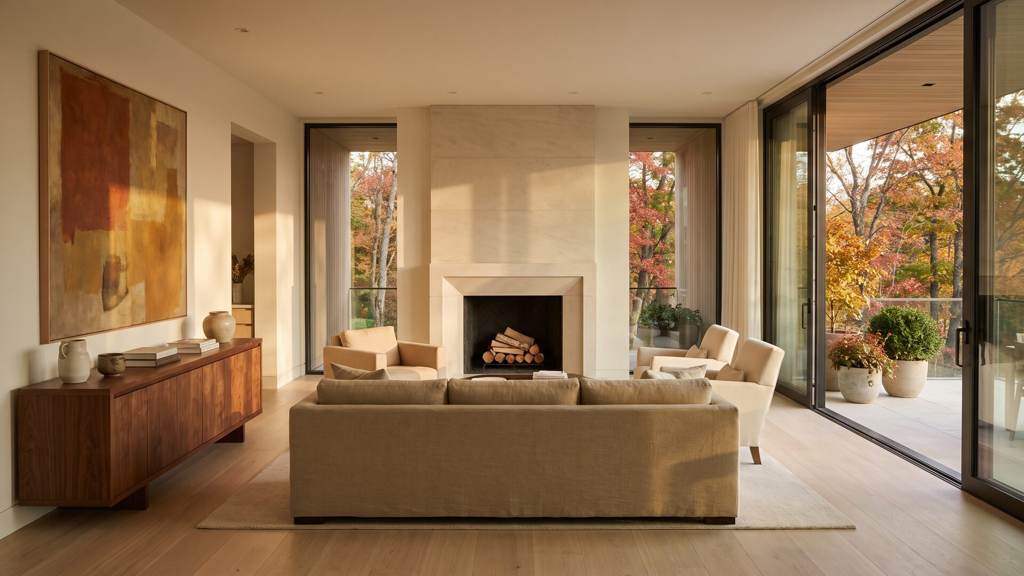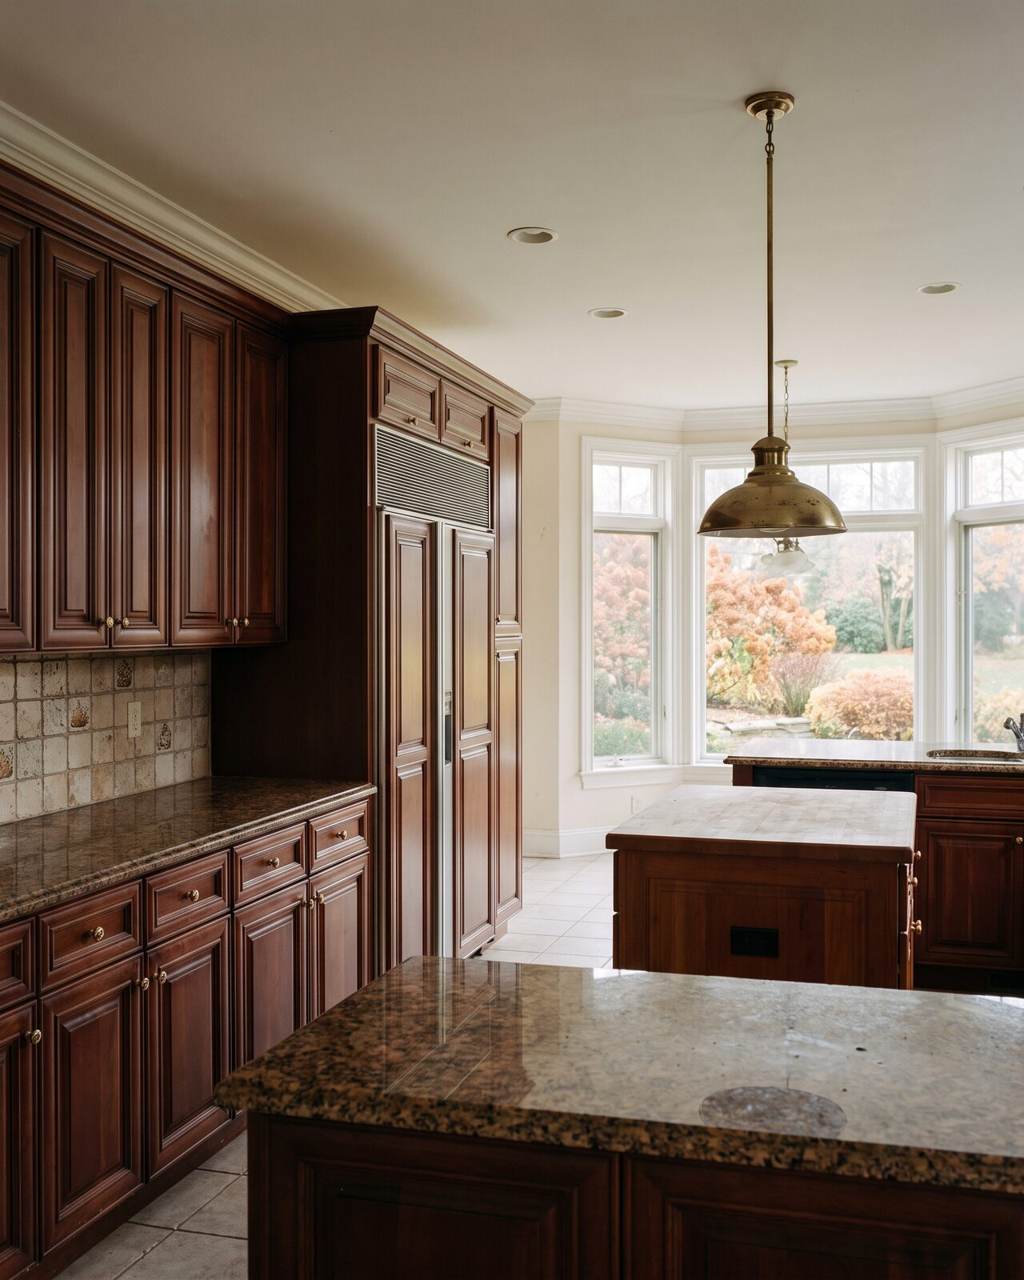

Ask most agents at the top of the market and they'll say there are really two selling seasons. One starts when spring does. The other starts the week after Labor Day and runs about fourteen weeks, to the New Year, and a big share of the year's serious deals get signed in it. This year it opens with prices where our mid-year report left them, on a plateau: still creeping up, not many sales, and held there mostly because there isn't much to buy.
This is our national outlook for that window. It covers what we expect the $700k-and-above segment to do between now and December 31, where the regional picture breaks from the national number, and what the calendar means if you plan to buy or sell before year end.
Our editorial desk compiled the baseline figures from the public data series listed under Sources and method at the end of this report. Anything describing the period after publication is a forecast, not a measurement. It's our reading of the evidence, with the probabilities we actually attach to it, and it can be wrong.
Where the market stands going into fall
- Median sale price, homes at $700k and above: up roughly 4% year over year through midsummer.
- Months of supply in the segment: about 3.5 months. That's loose by 2021 standards and tight by any longer history.
- Median days on market: near 50 days, roughly a week and a half slower than a year ago.
- Thirty-year fixed rate: in the mid-6% range for most of the first half, with the market pricing in a gradual drift lower.
- Cash share: still high, and the biggest reason the top of the market moves less violently than the entry level.
So nobody's panicking and nobody's overpaying. There just aren't many good houses, rates decide how many move-up sellers can afford to list, and a finished house is worth a lot more than an unfinished one right now.
Our base case for fall 2026
Our best guess is a fairly dull fall. We think it ends a little ahead of last year, and we'd be surprised by anything dramatic.
| Metric (national, $700k+) | Where it stands now | Our fall 2026 base case |
|---|---|---|
| Median sale price, year over year | +4% | +2% to +4% by December |
| Closed sales, year over year | Flat to down low single digits | +1% to +5% against a soft fall 2025 |
| New listings, September | n/a | Up mid single digits on fall 2025 |
| Months of supply | ~3.5 | 3.5 to 4.0, seasonally normal |
| Median days on market | ~50 | 55 to 65 by November |
| 30-year fixed rate | Mid-6% | Low-to-mid 6%, drifting rather than falling |
Here's why we think so.
Rates are coming down slowly. If you've got a 3% mortgage, trading it for a 6.5% one hurts. Every quarter that gap gets a bit smaller and a few more people decide they can live with it and list. That's a handful of extra listings a month, not a wave. You'll notice it most in the $700k-$1.5M band, where most buyers still finance. Above roughly $3M most people pay cash, so rates mostly just change the mood.
Sellers who sat out the spring will list in September. The September new-listing count usually tells you what the fall will look like, and everything we track (pre-list photography bookings, staging inventory, pre-inspection volume) points to a fuller September than 2025. More supply against a steady pool of buyers is why we expect slightly higher volume and slightly longer days on market at the same time.
The wealth effect is still there, but it's stopped accelerating. This segment runs on portfolios more than paychecks. Balance sheets are strong going into fall, which supports prices. They aren't growing fast enough to set off a fourth quarter of bidding wars.
The regional map is the real story
Honestly, the national number doesn't tell you much. It lumps together places going up and places going down. Selling in Greenwich this fall is nothing like selling in Naples.
| Region | Direction into year end | What is driving it |
|---|---|---|
| Northeast | Firmest in the country | Chronic under-building, near-zero new supply, high-single-digit price gains in the tightest suburbs |
| Midwest | Strong and underrated | Affordable relative to income, almost no speculative construction, steady in-migration of remote high earners |
| Mid-Atlantic | Steady | Deep professional employment base; DC-area demand tied to the federal budget calendar |
| Southeast (Florida) | Softest, and the source of any national weakness | Insurance and HOA carrying costs, condo-assessment overhang, high inventory in Gulf Coast metros |
| Texas and the Gulf | Flat to slightly negative | Sustained builder output; resale sellers competing against incentives they cannot match |
| Southwest (AZ, NV) | Flat | Completed-but-unsold spec inventory; Scottsdale-style incentive packages capping resale pricing |
| Mountain resort | Plateaued at a high level | Almost no developable land; feature-rich ski-in product still clears, dated product does not (see our Aspen report) |
| Pacific Northwest | Improving | Tech hiring stabilized; the most rate-sensitive of the western markets |
| Coastal California | Two-speed | Supply-constrained enclaves firm; higher-cost, higher-tax metros thin on volume |
The short version: where there's nothing to buy, prices are still going up, and where builders kept building, they're coming down. We think that gap gets wider this fall.
What will sell between September and December
The people shopping in the fall mostly have a date they're working to. Somebody's relocating, or the kids start at a new school, or they've already sold the other house, or there's a tax deadline. They want to move in and be done. So they'll pay for a kitchen that's already done, a wellness floor that's actually built (not a basement "with potential"), a real cellar. They don't have time to add any of that before the holidays.
The flip side is harsh. A project house listed in October asks a buyer to carry two properties through the winter and then start a renovation while material and labor costs are still high and good trades are booked months out. Buyers price all of that into their offer. In the first half of the year, comparable project houses traded 12-21% below their opening ask while finished homes in the same metros closed at or above final ask, and historically that spread widens in the fourth quarter.
And fall makes it worse, for three reasons:
- Autumn shows a house honestly. Bare trees, low sun and the first heating bills expose drainage, window performance and the age of the mechanicals in a way June doesn't. Inspectors find more, and buyers price it in.
- Presentation pays off more in October than in April. With less competing inventory, the gap between the best-presented home in a price band and the second-best gets bigger. Sellers who've kept up with the current palette and materials look current. Those who haven't look dated right when buyers are comparing carefully.
- Buyers can see the maintenance you put off. We wrote our fall maintenance checklist for owners, but if you're selling, read it as the list a buyer's inspector will work through.
Three scenarios, and our odds
| Scenario | Probability | Trigger | National price, year over year | Volume |
|---|---|---|---|---|
| Base: orderly autumn | ~60% | Rates drift in the low-to-mid 6% range; no macro shock | +2% to +4% | Up low single digits |
| Upside: early thaw | ~20% | A faster move toward high-5% mortgage rates | +5% or better, with bidding returning in scarcity metros | Up high single digits |
| Downside: risk-off | ~20% | An equity-market drawdown or a credit event | Flat to -2%, concentrated in Sun Belt metros | Down mid single digits |
If the bad case happens, it won't start in housing. It'll start in people's brokerage accounts (call it a balance-sheet event). A lot of these buyers watch their stocks more than their rate. That helped when rates jumped, and starter homes took the hit instead. It'd hurt if the market had a bad quarter. We'd keep an eye on stocks and credit spreads. Mortgage applications won't tell you much at this price.
The fall calendar
In the fall you've got a deadline, basically. Once the holidays hit, most of it's over.
| Window | What happens | What to do |
|---|---|---|
| Late August to Labor Day | Attention returns; agents preview | Finish the work. Nothing lists well half-done |
| Sept 8 to Sept 30 | The peak fall listing window; the best new inventory arrives | Sellers list here. Buyers see maximum choice and minimum leverage |
| October | Serious buyers engage; spring's leftovers cut prices | The best-balanced window for buyers, with real choice and real negotiation |
| Nov 1 to Thanksgiving | Volume thins; only motivated parties remain | Peak buyer leverage. Deadline-driven sellers negotiate hardest |
| Thanksgiving to Dec 31 | Very few listings; year-end tax and trust deadlines close deals | Slow and opportunistic, and the strongest window for an off-market approach |
What this means for you
If you're buying, look in September and negotiate in November. Get your financing fully underwritten now, not just pre-approved. In a thin market, being able to close in three weeks is worth more than another 2% off the ask, and it's the one edge a financed buyer can have over a cash buyer. Be honest with yourself about renovation. The discount on a project house is real, but so are the cost and the wait. And check the full days-on-market history instead of the current listing date, because relisting a home to reset the clock is the most common trick in a fall market. Our buying guides walk through the diligence steps.
If you're selling, this fall will pay a real premium for a finished, well-equipped home in a supply-constrained metro. It won't pay for square footage, deferred maintenance or a spring price carried forward. Price to the last 60 days of comparable sales, not the number you had in mind in May. If you can't be truly ready by the third week of September, use the fall to finish the work and list in spring, since the seasonal advantage is worth less than the finished-home premium. We make the full case in our piece on whether this is the moment to sell.
If you're holding, nothing here argues for hurrying. Scarcity is doing the work, and if you have no reason to sell, we won't invent one.
Sources and method
Where the numbers come from, so you can check them:
- Mortgage rates: Freddie Mac's weekly 30-year fixed survey (https://www.freddiemac.com/pmms).
- Prices and days on market for the top tier: Redfin's Luxury Market Report and its Data Center downloads (https://www.redfin.com/news/data-center/).
- Sales, inventory and months of supply: NAR's Existing-Home Sales numbers and price-tier tables (https://www.nar.realtor/research-and-statistics/housing-statistics/existing-home-sales), checked against Realtor.com's monthly inventory data (https://www.realtor.com/research/data/).
- Regional direction: the S&P CoreLogic Case-Shiller indices. We use them as a gut check, since they aren't a luxury series.
- New construction and builder incentives: Census and HUD's New Residential Construction release (https://www.census.gov/construction/nrc/).
- Fed meeting dates and rate projections: the FOMC calendar (https://www.federalreserve.gov/monetarypolicy/fomccalendars.htm).
When we say "the segment," we mean single-family sales at $700,000 and above, nationally, so anyone can rerun the numbers. The odds on the scenarios are our call, not a model's. They add up to 100%, and we put them in print so you can hold us to them. We'll look back at this in the year-end report and say where we missed. If one of these sources revises a number, we'll change ours and say so rather than changing it without a note (our editorial standards explain how).
Reported by Harrison Vale, Real Estate Markets Editor, a former prime-market broker licensed since 2009. Nothing here is investment, tax or legal advice. Luxury Hôm has no financial interest in any property, brokerage or market named above.