Insurance used to be a closing-week chore. You called an agent, got a binder, and emailed it to the lender. On a lot of high-end homes now, it's the first call we'd make after the inspection is booked, and in some markets it's worth making before the offer goes in.
The reason is simple. A custom house costs a lot to rebuild, it often sits somewhere scenic and exposed, and carriers have become far more selective about exactly those risks. The Private Risk Management Association's 2025 Private Client Insurance Insights Survey of 250 high-net-worth homeowners found that one in five had struggled to get homeowners insurance, rising to 30% in high-risk states. Sixty-three percent had paid higher premiums, and more than half had accepted lower coverage or new exclusions.
That's the market a buyer walks into this winter. Here's how we'd handle it.
Get a written quote while you still have options
Your lender needs proof of insurance before it funds the loan, so the policy has to exist by closing. The smart move is to know it can exist much earlier, ideally while your inspection contingency is still open.
Call a broker who places high-value homes every week, in addition to whoever writes your car policy. The private-client carriers usually want an in-person appraisal of the house for rebuild cost, and they'll ask about details a standard quote form skips: roof age and material, wiring and plumbing updates, central-station alarm and water-leak monitoring, distance to a hydrant, a gated drive. Send the listing, the inspection report and the seller's disclosures as soon as you have them.
Get it in writing.
A friendly "we can probably write that" is worth very little if the carrier pauses new business in that ZIP code two weeks later. In wildfire, coastal or hail country we'd also ask your attorney about an insurance contingency, or at least set the inspection deadline so the quote lands inside it.
Ask the seller for the claims history
Every insurer you approach will pull the property's loss history. You should see it first.
That history lives in a CLUE report (Comprehensive Loss Underwriting Exchange), kept by LexisNexis. It shows up to seven years of homeowners claims tied to the address, with the date, the type of loss and the amount paid, including claims filed by earlier owners. Under the Fair Credit Reporting Act, only the owner, an insurer or a lender can order one, so the buyer has to ask the seller. Owners can get a free copy every 12 months.
Read it next to the inspection report. Two water claims on a house with a finished lower level tells you where to send the inspector, and why a carrier might hesitate. A clean report is good news, with one caveat: it only reflects insurers that report to the exchange.
Ask for the current declarations page too. It shows the carrier, the dwelling limit, the deductibles, and any wind or hail deductible written as a percentage of the dwelling limit. If the seller has received a nonrenewal notice, you want to hear about it now.
Rebuild cost is the number that matters
Purchase price and rebuild cost are two separate numbers, and on a high-end home they can sit far apart in either direction. A lakefront teardown sells for the land. A stone house with hand-carved millwork, a slate roof and a curved staircase can cost more to rebuild than the comps would ever suggest.
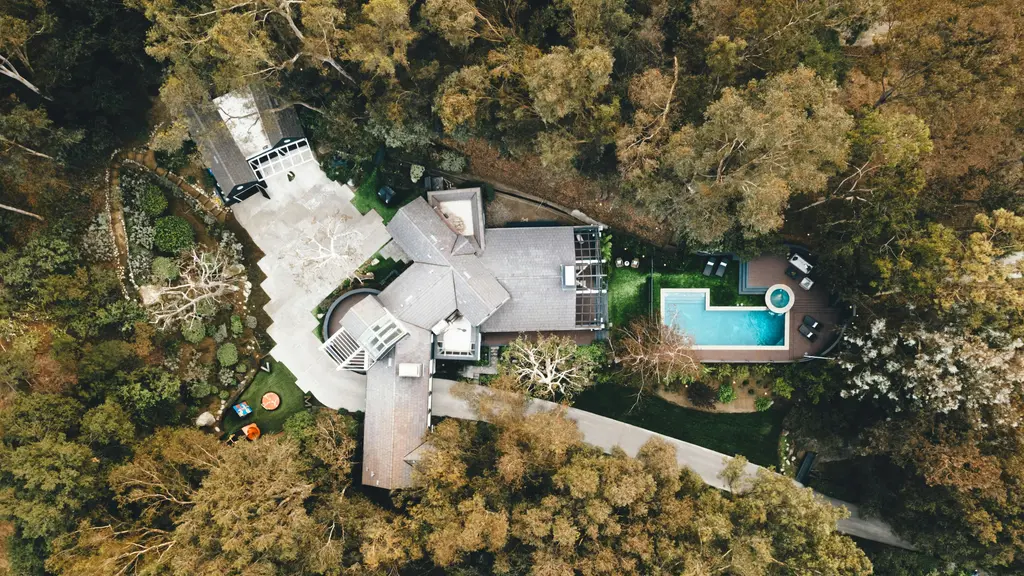
Write the policy to the rebuild figure. Check that the carrier's estimate counts what makes the house what it is: the plaster walls, the limestone terrace, the imported tile, the guest house, the pool house, the long drive and the stone wall along the road. Ask whether the policy includes extended or guaranteed replacement cost, and building-code upgrade coverage (usually called ordinance or law). An older house rebuilt to current code costs more than the original did, and that gap lands on you if the policy is silent.
For conforming loans, Fannie Mae's Selling Guide requires replacement-cost coverage on the home, while the roof only has to be insured, without that replacement-cost requirement. Jumbo lenders set their own requirements, so get your loan officer's list in writing early. Our jumbo mortgage rates guide covers how to shop those lenders.
What a FAIR Plan policy covers, and what it leaves out
In California, a buyer who can't place a standard policy may end up with the California FAIR Plan, the state's insurer of last resort. Go in with clear eyes. Its dwelling policy is named-peril: fire, lightning, internal explosion and smoke, with a few extras available for added premium. Theft, water damage and liability sit outside it, and combined coverage is capped per location at a level a large custom house can outgrow.
The usual answer is a difference in conditions policy, or DIC, from a private carrier. It wraps around the FAIR Plan and picks up the missing coverage. That means two policies, two deductibles and two claims departments, and the California Department of Insurance keeps a list of companies that write DIC coverage. Price both before you commit to a canyon or hillside house, and put the combined premium in your ownership math.
Florida has its own last-resort carrier, Citizens Property Insurance. Different state, same pattern: more paperwork, and coverage you'll want to read line by line.
Mitigation earns credits, so ask what's already done
California and Florida both tie premium discounts to specific, documented work on the house. Sellers who did that work should hand over the paperwork. Buyers should ask for it by name.
California's Safer from Wildfires regulation lists 10 actions that qualify for insurance discounts. Among them: a Class A fire-rated roof, a five-foot ember-resistant zone around the house (with metal fencing where a fence meets the walls), vents covered with 1/16- to 1/8-inch metal mesh, enclosed eaves, multi-pane windows, and defensible space that meets state and local rules. Wood shake shingles fall outside the Class A rating, so a shake roof is worth flagging early.
In Florida, credits on the wind portion of the premium run through the Uniform Mitigation Verification Inspection Form, OIR-B1-1802. The Office of Insurance Regulation put an updated version in effect April 1, 2026, and a completed form stays valid for up to five years as long as the structure hasn't materially changed. If the seller has a recent one, get a copy. If not, we'd order the inspection during your inspection window. It records roof shape, roof-deck attachment and roof-to-wall connections, which are exactly the things you can't judge from the driveway.
Flood and earthquake need their own policies
Most homeowners policies exclude flood. FEMA says so plainly, and a water-view house is where that gap costs the most. If the property is near a lake, river or coast, sits low on its lot, or falls in a mapped flood zone, price flood coverage as its own line item.
There's a useful timing rule here. A National Flood Insurance Program policy bought in connection with a mortgage closing takes effect at closing, skipping the usual 30-day wait, as long as the application and premium are in by then. NFIP building limits are modest next to the rebuild cost of a large home, so ask your broker about private or excess flood on top.
Earthquake works the same way in California and the Pacific Northwest: a separate policy, usually with a percentage deductible.
Bring the premium into the price conversation
Annual premium is a carrying cost, the same as property tax, and it belongs in your offer math from the start. A house that needs a FAIR Plan policy plus a DIC wrap, or sits on a barrier island, costs more to own every year than a similar house a few miles inland.
It can also be leverage. If the carrier wants a new roof before it'll bind, or the quote comes back far above what the seller pays today, treat it like an inspection finding and take it back to the table. Our guide on how to negotiate on a luxury home covers how to raise it.
The checklist we'd use
- Call a high-value insurance broker the week your offer is accepted, or before you write it in wildfire or coastal areas.
- Ask the seller for a CLUE report and the current declarations page, and ask directly about nonrenewal notices.
- Get a written quote built on rebuild cost, with extended replacement cost and ordinance or law spelled out.
- Collect mitigation paperwork: wildfire work in California, an OIR-B1-1802 form in Florida.
- Price flood, and earthquake where it applies, as separate policies.
- Get your lender's insurance requirements in writing and confirm the binder is in their hands several days before closing.
If you're closing in December, start on step one sooner than feels necessary. Carriers, underwriters and lenders all slow down around the holidays. Our guide to buying a luxury home in winter covers the rest of the off-season calendar.